California Insurance Fraud Prevention: Powerful 2026 Bills Target Claims Abuse
September 18, 2026 | JacobiJournal.com — Insurance fraud prevention is becoming an increasingly important part of California’s effort to strengthen the integrity of residential property insurance claims. Six major insurance measures approved during the 2026 legislative session and placed on Gov. Gavin Newsom’s desk would change how insurers document, investigate, communicate, and resolve certain property claims. The measures address wildfire smoke damage, residential policy renewals, consumer information, disaster recovery, claim-related documents, and claims-handling deadlines. Although the bills are not fraud prosecutions themselves, several could have significant consequences for insurance fraud prevention because clearer documentation, standardized claims procedures, regulatory oversight, and more transparent records can make questionable conduct easier to identify and investigate. The connection between these reforms and insurance fraud prevention is particularly important after California’s recent wildfire disasters. Insurance claims generated after catastrophic events can involve complicated damage assessments, competing expert opinions, incomplete documentation, disputed losses, and substantial financial pressure on both insurers and policyholders. California’s Department of Insurance has already taken enforcement action after investigating wildfire claims and has separately advanced legislation intended to establish more consistent standards. The department’s September 2 legislative package described the broader effort as one focused on disaster recovery, insurer accountability, transparency, and consumer protection. Those objectives also create a stronger environment for insurance fraud prevention, because reliable claims records and enforceable standards provide investigators with clearer evidence when conduct crosses the line from legitimate dispute into potential fraud. Six Bills Could Strengthen Insurance Fraud Prevention AB 1795, the Smoke Damage Recovery Act, is one of the most significant measures because it would establish consistent standards for investigating and resolving wildfire smoke-damage claims involving standing residential properties. The legislation would create a rebuttable presumption that smoke, ash, soot, char, or combustion byproducts found in a surviving residence within a wildfire impact zone are connected to the wildfire. It would also address testing costs, additional living expense coverage, inspection requirements, and restoration standards. From an insurance fraud prevention perspective, standardized testing and restoration rules could reduce the uncertainty that sometimes surrounds smoke-related claims and create a more consistent evidentiary record for determining whether claimed damage actually exists and what remediation is necessary. AB 2038 approaches the issue from the policy-continuity side of residential insurance. The measure would require an insurer to renew residential property insurance for specified periods following a total loss and would restrict certain cancellations or nonrenewals involving properties located within or adjacent to wildfire perimeters for a specified period after a state of emergency. While the measure is primarily a consumer-protection proposal rather than an anti-fraud statute, its significance for insurance fraud prevention comes from the importance of maintaining an accurate and traceable insurance record after a catastrophe. Clear rules concerning when a policy can be renewed, canceled, or nonrenewed can make it easier to distinguish legitimate underwriting decisions from questionable conduct and can reduce uncertainty surrounding the status of coverage after a major loss. SB 354, the Insurance Information and Privacy Protection Act, would update California’s insurance privacy framework by establishing standards concerning how insurers and related parties process and share consumer information. That has a direct connection to insurance fraud prevention because modern insurance investigations depend heavily on information systems, claims records, policyholder data, third-party service providers, and electronic communications. Stronger rules governing information use can help create a more accountable environment in which legitimate fraud investigations can occur without leaving consumer information exposed to unauthorized use. The measure is particularly relevant as insurance companies increasingly rely on technology and outside vendors to process claims and evaluate risk. SB 876, the Disaster Recovery Reform Act, would establish additional requirements affecting disaster claims and recovery. The legislation would address building-code upgrade costs, extended additional living expense coverage, and other financial protections for policyholders recovering from disasters. The Department of Insurance has described the broader disaster-recovery package as an effort to speed recovery and strengthen accountability. From an insurance fraud prevention standpoint, clearly defined benefits and recovery standards can help reduce ambiguity surrounding what an insurer must provide and what a claimant is entitled to receive. When coverage rules and payment obligations are clearly documented, investigators and regulators have a stronger basis for evaluating whether a disputed claim reflects a legitimate disagreement, an administrative failure, or conduct requiring further scrutiny. Claims Transparency Creates a Stronger Evidence Trail SB 877 and SB 878 are especially relevant to insurance fraud prevention because both address the information and timing surrounding insurance claims. SB 877 would require insurers to provide claim-related documents, including preliminary and final copies of specified materials, within 15 calendar days after a request following a loss. Greater access to claim documentation can help policyholders, regulators, attorneys, and investigators compare how a loss was initially evaluated with how the claim was ultimately handled. That documentation can be important when determining whether an apparent discrepancy represents a reasonable revision, an administrative mistake, a coverage disagreement, or potentially intentional manipulation of claim information. SB 878 would codify specified claims-handling requirements concerning communications, claim acknowledgment, review, proof of loss, and payment. The measure would also impose consequences involving interest when certain payments are delayed. These requirements matter to insurance fraud prevention because a defined claims timeline creates a more objective record of what happened after a loss was reported. Investigators can more readily establish when a claim was received, when the insurer began reviewing it, what information was requested, when a decision was made, and whether an undisputed amount was paid within the applicable period. A reliable chronology can become an important component of an investigation when regulators examine allegations of improper claims handling or other misconduct. The importance of transparent claim records is underscored by California’s 2026 enforcement action involving State Farm’s handling of residential claims arising from the Los Angeles wildfires. The Department of Insurance said its market conduct examination reviewed 220 claims and identified 398 violations in 114 of those claims, with many claims containing multiple violations. The department alleged problems involving investigation deadlines, claim determinations, and payment requirements and filed
California Continues Enforcement Against Workers Compensation Billing Fraud

September 14, 2026 | JacobiJournal.com — Workers compensation billing fraud remains an important enforcement concern in California, particularly when medical providers allegedly submit bills for unnecessary treatment, use improper medical codes, or participate in financial arrangements involving bribes or kickbacks. The California Department of Industrial Relations (DIR) identifies these activities as examples of fraud affecting the state’s workers’ compensation system. Workers compensation billing fraud does not necessarily appear as a single dramatic criminal case. It can emerge through questionable billing patterns, inappropriate medical services, inaccurate coding, referral arrangements, or financial relationships that improperly influence treatment or reimbursement. DIR maintains fraud-prevention resources and reporting mechanisms for suspected medical-provider fraud, while also working with other state agencies involved in insurance fraud enforcement. Medical Billing Remains a Key Fraud Concern Workers compensation billing fraud can affect the system when medical providers submit claims for services that are unnecessary, inappropriate, inaccurately coded, or otherwise unsupported. DIR specifically lists providers who bill for inappropriate or unnecessary treatment among the categories of workers’ compensation fraudsters it seeks to address. The concern extends beyond the amount of a single bill. Medical treatment is a central component of workers’ compensation, and billing decisions can influence insurer payments, lien disputes, treatment reviews, and the overall cost of claims. When billing is intentionally manipulated, investigators may need to examine medical records, billing data, treatment patterns, and relationships among the individuals or entities involved. Improper Medical Codes Can Trigger Fraud Concerns Workers compensation billing fraud can also involve the submission of bills using improper medical codes. Medical codes communicate information about services, procedures, diagnoses, and other aspects of a medical claim, making accurate coding important to the reimbursement process. DIR specifically identifies bills submitted with improper medical codes as one form of medical-provider fraud. A coding discrepancy does not automatically establish criminal fraud. Coding errors can occur for legitimate administrative reasons, and an investigation must distinguish an inadvertent mistake from intentional conduct. Where investigators believe improper coding was knowingly used to obtain an improper payment, however, the billing records can become important evidence in a broader fraud investigation. Unnecessary Treatment Can Become an Investigative Issue Another category identified by DIR involves billing for inappropriate or unnecessary treatment. Workers compensation billing fraud allegations involving treatment can require investigators to examine whether the services billed were actually provided, whether they were medically appropriate, and whether the documentation supports the services represented on the claim. The issue is particularly significant because injured workers legitimately require medical treatment after workplace injuries. Enforcement must therefore distinguish legitimate treatment decisions from fraudulent billing practices. A disagreement over medical necessity, standing alone, should not be characterized as proof of fraud; investigators must establish the facts and circumstances surrounding the treatment and billing. Bribes and Kickbacks Are Serious Warning Signs DIR also identifies the payment of bribes or kickbacks as conduct associated with workers’ compensation fraud by medical providers. Financial arrangements that improperly influence referrals, treatment, or billing can undermine the independence of medical decision-making and potentially generate claims that would not otherwise have occurred. Kickback allegations can also broaden an investigation beyond one provider or one patient. Investigators may examine whether money or another benefit was exchanged for patient referrals, whether treatment decisions were influenced, and whether reimbursement claims were generated as a result. The financial relationships surrounding medical services can therefore become an important part of a workers compensation billing fraud investigation. California Uses Multiple Fraud-Prevention Mechanisms DIR maintains a dedicated Fraud Prevention program addressing several categories of misconduct affecting California workers. The department states that fraud can include inaccurate payroll reporting by employers, fraudulent workers’ compensation claims, and abuse of injured workers by medical providers. The department also provides specific channels for reporting suspected medical-care-provider fraud. Those resources allow allegations to be directed to the appropriate enforcement authorities rather than relying solely on ordinary claims administration. This structure reflects California’s broader approach of combining fraud detection, investigation, regulatory action, and prosecution when the available evidence supports further enforcement. Medical Providers Are Subject to Fraud Oversight Workers compensation billing fraud involving medical providers can have consequences within the workers’ compensation system even when a matter does not immediately result in a criminal conviction. DIR’s Anti-Fraud Unit handles provider suspensions under Labor Code section 139.21 and lien stays involving criminally charged providers under Labor Code section 4615. DIR also maintains public resources concerning suspended providers, criminally charged providers whose liens have been stayed, dismissed liens, and other fraud-related proceedings. These mechanisms allow the agency to address provider participation in the workers’ compensation system while criminal investigations or other enforcement proceedings move forward. Provider Suspensions Can Affect Workers Compensation Participation DIR’s fraud-prevention system includes an Anti-Fraud Unit responsible for suspending physicians, practitioners, and providers from participating in the workers’ compensation system under Labor Code section 139.21. The department also identifies procedures involving liens connected with criminally charged providers. These administrative mechanisms are separate from the question of whether a particular provider ultimately faces or is convicted of a crime. A provider suspension can affect participation in the workers’ compensation system while other legal proceedings continue. This distinction is important when reporting workers compensation billing fraud because administrative enforcement and criminal prosecution are not interchangeable. Fraud Investigations Can Extend Beyond Billing Records Workers compensation billing fraud investigations may require more than reviewing invoices. Investigators can examine medical records, treatment documentation, patient histories, billing codes, reimbursement information, referral arrangements, and communications surrounding the services at issue. The purpose of examining multiple records is to establish whether the billing information accurately represents the underlying medical activity. A bill that appears unusual may require additional context before investigators can determine whether there is evidence of intentional wrongdoing. That evidence-based approach is particularly important when medical professionals and legitimate patient care are involved. Patterns Can Be More Significant Than Individual Errors An isolated billing mistake may not provide enough information to establish workers compensation billing fraud. Repeated patterns can present a different investigative question, particularly when the same coding problems, treatment irregularities, or
Former Orange County Judge Faces Key Sentencing Recommendation in Workers’ Compensation Fraud Case
August 28, 2026 | JacobiJournal.com — Former Orange County Superior Court Judge Israel Claustro is facing a federal sentencing recommendation of probation after pleading guilty to mail fraud connected to a scheme involving California’s workers’ compensation system. Federal prosecutors recommended a one-year term of probation and a $5,000 fine, according to reporting published August 21, 2026. The recommendation follows Claustro’s guilty plea and resignation from the Orange County Superior Court bench. Claustro pleaded guilty in January 2026 to one count of mail fraud after federal prosecutors accused him of participating in a scheme involving the California Subsequent Injuries Benefits Trust Fund, which provides benefits within the state’s workers’ compensation system. The federal charge carries a statutory maximum of 20 years in prison, although prosecutors are recommending a substantially lower sentence. The sentencing recommendation represents a significant development in a case that has already resulted in Claustro’s resignation as a judge and disciplinary action by California’s judicial oversight authorities. Federal Prosecutors Recommend Probation Federal prosecutors have recommended that Claustro receive one year of probation rather than a prison sentence. The recommendation also calls for a $5,000 fine, according to the August 21 report concerning the government’s sentencing position. Under the federal sentencing calculations described in the report, Claustro could otherwise face a guideline range involving four to 10 months of imprisonment and a fine between $2,000 and $20,000. The recommended reduction reflects factors including his early acceptance of responsibility and agreement to resign from judicial office. The recommendation does not constitute the final sentence. The federal court will determine the appropriate sentence after considering the applicable law, sentencing guidelines, plea agreement, government recommendation, and other relevant information. The development therefore represents a sentencing recommendation rather than a completed sentencing proceeding. Claustro Pleaded Guilty to Mail Fraud Federal prosecutors charged Claustro with one count of mail fraud in January 2026. The charge alleged that he defrauded California’s workers’ compensation program through conduct involving Liberty Medical Group Inc., a Rancho Cucamonga-based medical corporation he operated. According to the U.S. Department of Justice, Claustro was not a physician or other medical professional but operated Liberty Medical Group while serving as an Orange County prosecutor. Federal prosecutors alleged that the company submitted medical reports and related materials in connection with workers’ compensation matters. Claustro agreed to plead guilty and resign from his position as an Orange County Superior Court judge. He formally entered his guilty plea on January 12, 2026, in federal court in Santa Ana. The guilty plea distinguishes the case from a prosecution involving disputed allegations. Claustro admitted criminal responsibility for the federal mail fraud offense as part of the plea process. The Scheme Involved California’s Workers’ Compensation System The federal case centers on alleged fraudulent conduct involving California’s Subsequent Injuries Benefits Trust Fund, commonly known as SIBTF. SIBTF provides benefits within California’s workers’ compensation system to qualifying injured workers who have a preexisting disability or impairment and subsequently sustain another disabling injury. Federal prosecutors alleged that Claustro’s company submitted medical reports connected to SIBTF claims. According to the federal case materials, Claustro paid Dr. Kevin Tien Do to prepare medical reports after Do had been suspended from participating in California’s workers’ compensation program. Prosecutors alleged that other doctors’ names were used on billing forms and reports to conceal Do’s involvement. The allegations placed the conduct directly within the broader workers compensation fraud enforcement landscape because the alleged scheme involved medical documentation submitted in connection with benefits from a California workers’ compensation program. Prosecutors Identified Financial Loss to SIBTF Federal prosecutors estimated that the loss attributable to Claustro’s participation was approximately $38,670. The amount represented payments made by SIBTF to Liberty Medical Group based on reports that Claustro knew had been prepared by Do after Do’s suspension from the workers’ compensation program. The broader financial activity involving Liberty was substantially larger. Prosecutors said SIBTF paid more than $3 million to the company based on its billings, while the specific loss amount attributed to Claustro’s conduct was approximately $38,670. That distinction matters when reporting the case. The total amount billed or paid through the company should not automatically be characterized as the criminal loss attributable to Claustro. Former Judge Also Resigned From the Bench Claustro’s federal plea agreement required him to resign from his position as an Orange County Superior Court judge. He had been elected to the Superior Court in 2022 and served in the Family Law Court. His alleged conduct occurred before he became a judge, while he was working as a prosecutor with the Orange County District Attorney’s Office. Claustro’s attorney said that his client deeply regretted his participation in the business venture, accepted responsibility, and cooperated with the investigation. The defense has characterized the conduct as a business venture that did not involve Claustro’s work as a prosecutor or judge. The resignation became an important part of the federal plea agreement and later judicial disciplinary proceedings. Judicial Discipline Followed the Guilty Plea Claustro also faced consequences from California’s judicial oversight system. The Commission on Judicial Performance issued a public censure and barred him from future judicial office. The commission concluded that his felony conduct brought the judicial office into disrepute and also found that he failed to promptly report the federal criminal charge as required. The disciplinary action is separate from the federal criminal sentencing process. That distinction is important because the August sentencing recommendation concerns the federal mail fraud case, while the censure and bar from future judicial service resulted from proceedings before California’s judicial disciplinary authority. Workers Compensation Fraud Involved a Suspended Doctor The federal case also involved Dr. Kevin Tien Do, who prosecutors identified as a participant in the scheme. Do previously pleaded guilty to federal charges involving conspiracy to commit mail fraud and subscribing to a false tax return. According to prosecutors, Do had been suspended from California’s workers’ compensation program following a prior health care fraud conviction. Federal prosecutors alleged that Claustro knew Do had been suspended but nevertheless paid him to prepare medical
San Francisco Contractors Face Compensation Fraud Charges After Injured Worker’s Claim Is Allegedly Denied
August 26, 2026 | JacobiJournal.com — Compensation fraud allegations are at the center of a felony case against San Francisco contractors Declan and Grace McKevitt, who prosecutors accuse of workers’ compensation premium fraud, payroll tax violations, and an effort to prevent an injured employee from pursuing compensation. The San Francisco District Attorney’s Office announced the charges on August 7, 2026. According to prosecutors, the allegations involve the underreporting of payroll, failure to make required insurance and tax payments, and statements concerning a worker who suffered a serious workplace injury. The case is significant because the allegations involve multiple aspects of the workers’ compensation system. Prosecutors contend that the defendants’ conduct included alleged financial misrepresentation involving insurance premiums as well as an alleged attempt to interfere with an injured worker’s compensation claim. Both defendants pleaded not guilty. The charges remain allegations, and the prosecution must establish the alleged offenses through the criminal court process. Prosecutors Announce Felony Charges Against San Francisco Contractors According to the San Francisco District Attorney’s Office, Declan McKevitt, 47, and Grace McKevitt, 54, were arraigned on felony charges connected to alleged workers’ compensation premium fraud and payroll tax fraud. The defendants own and manage An Dun Construction, according to prosecutors. The case was investigated and charged by the San Francisco District Attorney’s Economic Crimes Unit. The allegations concern payroll information reportedly provided to a workers’ compensation insurance company and the California Employment Development Department. Prosecutors allege that the defendants underreported payroll and failed to pay required insurance premiums, income taxes, payroll taxes, and other contributions. The charges therefore extend beyond a disagreement concerning an insurance claim. Prosecutors allege a pattern of conduct involving the employer’s financial obligations and a separate dispute concerning an injured employee’s ability to pursue compensation. Payroll Underreporting Allegedly Reduced Insurance Obligations Workers’ compensation insurance premiums are affected by information concerning an employer’s payroll and workforce. Accurate payroll reporting allows insurers to calculate premiums based on the employer’s reported operations and exposure. Prosecutors allege that the McKevitts underreported payroll to their workers’ compensation insurance company and to the California Employment Development Department. The District Attorney’s Office also alleges that the defendants failed to make required insurance premium and tax payments. If proven, deliberate payroll underreporting can have consequences beyond the employer. Insurance premiums that do not reflect actual payroll can affect the financial calculations used to provide workers’ compensation coverage. The allegations are therefore relevant to the broader issue of compensation fraud because prosecutors contend that the alleged payroll practices affected the amount the business was required to pay while also involving additional alleged violations of California law. Injured Worker’s Claim Became Part of the Investigation The case also involves a serious workplace injury that prosecutors say brought the alleged conduct to investigators’ attention. According to the San Francisco District Attorney’s Office, an employee severely injured his hand while using a table saw, resulting in an amputated finger. Prosecutors allege that Declan McKevitt subsequently told the injured worker to deny that the injury was work-related while receiving medical treatment. Prosecutors further allege that McKevitt denied that the injured worker was an employee of An Dun Construction and claimed that the worker had been at the jobsite without his knowledge. Those allegations give the case an important compensation component. The prosecution is not limited to allegations concerning insurance premiums or payroll reporting. It also alleges conduct intended to prevent an injured employee from pursuing benefits following a workplace accident. Employment Records Allegedly Contradicted the Denial The San Francisco District Attorney’s Office said payroll records and witness statements indicated that the injured worker had been employed by An Dun Construction for approximately seven months before the accident. Prosecutors allege that the denial of the worker’s employment status resulted in a four-month delay in payment of benefits owed to the injured employee. Employment records can become important evidence when the existence of an employment relationship is disputed after a workplace injury. Payroll records, witness accounts, business documents, and other information can help investigators establish the circumstances surrounding an individual’s work for a company. In this case, prosecutors allege that the available records and witness statements contradicted the claim that the injured worker was not an employee. Those allegations remain subject to the criminal court process. Additional Insurance Fraud Counts Involve the Injury Claim Declan McKevitt faces two additional insurance fraud counts under California Insurance Code §1871.4(a)(1), according to prosecutors. The counts concern allegations that he made a false statement to deny compensation and discouraged the injured worker from claiming benefits or pursuing a workers’ compensation claim. These allegations distinguish the case from a premium dispute involving only payroll reporting. Prosecutors contend that the alleged conduct also affected the injured employee’s ability to obtain benefits following a serious workplace injury. The allegations are particularly relevant to compensation fraud enforcement because the prosecution claims that statements concerning the worker’s employment and injury were used in connection with the compensation claim. Multiple Payroll and Tax Charges Were Also Filed The McKevitts face additional charges involving payroll-related obligations and required contributions. According to the San Francisco District Attorney’s Office, both defendants face allegations involving insurance fraud under Insurance Code §11880(a), failure to make contributions under Unemployment Insurance Code §2108, acting to evade tax under Unemployment Insurance Code §2117.5, and failure to collect or pay over tax or other money under Unemployment Insurance Code §2118.5. Declan McKevitt’s two additional Insurance Code §1871.4(a)(1) counts relate specifically to the allegations involving the injured employee’s compensation claim. The range of charges reflects the prosecution’s allegation that the conduct affected several separate legal and financial obligations. The case consequently involves alleged insurance, payroll, and tax misconduct rather than a single isolated dispute. Both Defendants Pleaded Not Guilty Declan and Grace McKevitt pleaded not guilty to the charges announced by the San Francisco District Attorney’s Office. Bail was set at $40,000 for each defendant. According to prosecutors, both defendants posted bail and were subsequently released on their own recognizance. Their next court appearance is scheduled for
California Continues Insurance Fraud Enforcement Across Statewide Insurance Market
August 24, 2026 | JacobiJournal.com — California’s insurance regulators and law enforcement partners continue to treat insurance fraud as a significant consumer-protection and market-integrity issue. The California Department of Insurance’s 2026 enforcement record includes investigations and prosecutions involving fraudulent claims, staged collisions, agent misconduct, premium-related schemes, and other alleged attempts to obtain improper insurance payments. The Department’s official 2026 records show that its Investigation Division remains responsible for investigating and prosecuting insurance fraud while also addressing unlicensed insurance activity and misconduct involving insurance professionals. The agency describes its investigators as a frontline enforcement resource for California’s insurance marketplace. Although the Department did not announce a separate statewide fraud sweep on August 24, its 2026 enforcement record demonstrates that insurance fraud investigations remain active across multiple categories. That distinction matters: this article is an enforcement update based on documented agency activity, rather than a claim that California announced a new statewide fraud operation on August 24. Department Records Show Multiple Fraud Categories California’s Department of Insurance categorizes its enforcement announcements by subject, including automobile fraud, other fraud investigations, and workers’ compensation fraud investigations. The agency’s 2026 subject index lists cases involving staged automobile collisions, fraudulent insurance claims, insurance-agent misconduct, and workers’ compensation-related fraud. The record also shows that the Department continues to use criminal investigations and prosecutions as part of its broader consumer-protection responsibilities. This broad enforcement structure reflects the different ways insurance fraud can affect California policyholders and insurers. Fraud can occur when someone allegedly submits a false claim, deliberately stages an accident, conceals information relevant to premiums, or uses an insurance position to improperly obtain money. Not every disputed claim or billing error constitutes fraud. Criminal fraud generally requires evidence supporting intentional misconduct, and allegations must be distinguished from convictions or final judicial findings. July Enforcement Included a San Jose Fraud Conviction One of the Department’s most recent fraud-specific announcements during July involved a San Jose driver who was sentenced after investigators uncovered a fraudulent insurance claim connected to a road-rage incident. The Department announced on July 10 that Kenneth Pham Tran, 54, of San Jose, was sentenced after dashcam footage showed him initiating a road-rage incident that resulted in his vehicle being rear-ended by a semi-truck. Authorities said Tran subsequently attempted to profit from the collision by submitting a fraudulent insurance claim. Tran received 60 days in county jail, two years of probation, and an order to pay more than $4,000 in restitution, according to the Department. The case demonstrates how evidence obtained from ordinary sources, including dashcam footage, can become important in an insurance fraud prosecution. It also illustrates the connection between fraudulent claims and broader public-safety concerns when an incident is deliberately created or manipulated. Insurance Fraud Enforcement Extends Beyond Auto Claims The July enforcement record demonstrates that California’s insurance fraud efforts extend beyond automobile claims. The Department of Insurance also investigates workers’ compensation fraud, premium fraud, agent misconduct, and other conduct involving insurance transactions. Workers’ compensation cases can be particularly significant because alleged fraudulent conduct may affect employers, insurers, injured workers, and the cost of maintaining coverage. Premium-related investigations can involve allegations that employers intentionally misreported payroll or other information used to calculate insurance premiums. These cases differ from fraudulent injury claims, but they remain part of the broader insurance-fraud enforcement framework maintained by California authorities. Workers’ Compensation Premium Investigations Remain Important The Department of Insurance maintains specific resources for investigating workers’ compensation premium fraud. The agency identifies payroll underreporting, employee misclassification, and other deliberate misrepresentations as potential forms of premium fraud. The distinction between an administrative mistake and intentional fraud remains important. An incorrect payroll figure does not automatically establish criminal conduct. Investigators must examine the circumstances and evidence to determine whether an intentional effort to avoid premiums occurred. When investigators do establish evidence of deliberate misrepresentation, however, the matter can become a criminal insurance-fraud investigation. This enforcement approach is important because improperly reduced premiums can potentially create an unfair advantage for businesses that do not accurately report their workforce compared with employers that comply with insurance requirements. Insurance Agent Misconduct Also Draws Scrutiny California’s enforcement responsibilities also include investigations involving licensed insurance professionals. Agent-related misconduct can involve allegations of premium theft, fraudulent policies, misappropriation of client funds, or other unlawful activity. Because insurance agents often serve as intermediaries between consumers and insurers, misconduct can affect both individual policyholders and insurance companies. The Department’s 2026 enforcement records include investigations involving insurance professionals, demonstrating that enforcement is not limited to fraudulent claims submitted by policyholders. For consumers, this makes it important to verify insurance information, retain documentation, and promptly question unusual requests for payments or policy information. Fraud Investigations Protect Legitimate Policyholders The purpose of insurance fraud enforcement extends beyond recovering money for insurers. Fraud can also affect legitimate policyholders by increasing costs and undermining confidence in the insurance system. When fraudulent claims or deliberately inaccurate information result in improper payments, insurers may face losses that ultimately become part of the broader cost of providing coverage. Enforcement can therefore serve a deterrent function. Investigations and prosecutions communicate that deliberate attempts to manipulate insurance systems can result in criminal consequences. At the same time, enforcement must remain evidence-based. Legitimate disputes between policyholders and insurers should not automatically be characterized as fraud. California Uses Multiple Sources of Evidence Modern fraud investigations can involve substantially more than traditional paper insurance records. The San Jose road-rage case demonstrates how video evidence can become important in an investigation. In other cases, investigators may examine financial records, insurance applications, payroll documentation, medical records, claim histories, communications, photographs, and other evidence. The type of evidence depends on the suspected conduct. For example, an automobile insurance fraud investigation may focus on accident footage, vehicle damage, witness statements, and claim documentation. A workers’ compensation premium case may instead require payroll records, tax information, employee classifications, and insurance audits. The investigative process therefore varies considerably from one case to another. Enforcement Does Not Mean Every Claim Is Suspicious California’s continued enforcement activity should not
Southern California Towing Companies Face Nearly $6 Million Workers Compensation Premium Fraud Case
August 21, 2026 | JacobiJournal.com — Two Southern California towing company owners were arrested in March after the California Department of Insurance alleged that they participated in a scheme designed to reduce their workers’ compensation insurance premiums through payroll concealment and other misrepresentations. The California Department of Insurance announced the arrests on March 11, 2026, identifying the case as a nearly $6 million insurance fraud scheme. The department alleged that the owners of two towing businesses manipulated payroll information and used a shell company as part of an effort to reduce the amount of workers’ compensation premiums they were required to pay. The case remains relevant to California insurance fraud coverage because it illustrates how alleged employer misrepresentations can affect the workers’ compensation insurance market. It also provides a concrete example of the type of employer conduct that California investigators classify as potential premium fraud. Importantly, the allegations remain allegations unless and until established through the legal process. Alleged Payroll Concealment at the Center of the Case According to the Department of Insurance, the investigation began after an insurer submitted suspected fraud referrals concerning the towing businesses. Investigators allegedly found significant discrepancies between payroll reported to the insurance carrier and payroll that the businesses actually paid. The department alleged that the owners used a shell company to conceal wages and underreported employee payroll in insurance records. A forensic audit reportedly identified approximately $16.7 million in actual payroll, compared with roughly $3 million reported to the insurer. Investigators alleged that the resulting difference contributed to approximately $5.9 million in unpaid workers’ compensation insurance premiums. Those figures are central to understanding the scale of the alleged scheme. The case is not simply about an incorrect insurance form or an isolated payroll mistake. Investigators allege a broader pattern involving payroll reporting and business structures that affected the premiums owed for workers’ compensation coverage. That is precisely the type of conduct California identifies as potential workers compensation premium fraud. How Premium Fraud Can Work Workers’ compensation insurance premiums are influenced by information provided by employers, including payroll and other factors used by insurers to calculate the cost of coverage. When an employer deliberately reports less payroll than it actually pays, the insurer may calculate premiums using an artificially reduced exposure. California’s Department of Insurance specifically identifies underreporting the number of employees or wages paid, misclassifying employee work, and manipulating experience modification information as examples of workers’ compensation insurance premium fraud. The alleged Southern California towing case fits within that broader category because investigators contend that payroll was deliberately concealed or underreported. The financial consequences can extend beyond the immediate insurer. When a business allegedly avoids premiums that should have been paid, competitors that accurately report payroll may face an uneven business environment because they continue paying the premiums associated with their actual workforce. Investigation Began With Fraud Referrals The case also demonstrates how suspected insurance fraud can enter the investigative process. According to reporting on the California Department of Insurance investigation, the department received referrals from an insurance carrier concerning the towing businesses. The investigation expanded after additional information allegedly connected the two businesses and raised further questions about payroll reporting. California maintains a formal process for reporting suspected workers’ compensation premium fraud. The Department of Insurance explains that referrals can involve allegations such as payroll underreporting, payroll misclassification, and experience modification evasion. After a referral is submitted, CDI reviews the information to determine whether the matter should be assigned for investigation, referred to another agency, or closed because of insufficient evidence or resources. This process is important because a referral itself does not establish fraud. Investigators must evaluate the underlying evidence before determining whether a case warrants further action. Forensic Audits Can Reveal Payroll Discrepancies The alleged difference between reported and actual payroll illustrates why financial audits can be important in workers compensation premium fraud investigations. Insurance investigators may need to compare payroll records, tax documents, employee information, bank records, insurance applications, and other business documentation to determine whether reported information accurately reflects the employer’s operations. A forensic audit can help identify discrepancies that might otherwise be difficult to detect through routine claims handling. In the towing case, investigators reportedly determined that the businesses’ actual payroll was substantially higher than the amount reported to the insurer. The alleged discrepancy became a central part of the fraud investigation. Such evidence can be particularly significant when prosecutors seek to establish that an inaccurate insurance representation was intentional rather than an ordinary accounting or administrative error. Shell Company Allegations Add Complexity The alleged use of a shell company adds another dimension to the case. According to the Department of Insurance investigation, the owners allegedly concealed payroll through another business structure while reporting substantially lower payroll to their workers’ compensation insurer. Business structures themselves are not illegal. Companies can legitimately establish subsidiaries, affiliates, or separate entities for numerous lawful purposes. The issue in an insurance fraud investigation is whether those structures were allegedly used to conceal information that an insurer was entitled to receive when determining premiums. That distinction is essential when reporting the case. The allegations concern the purported use of business arrangements to misrepresent payroll and insurance exposure, not the mere existence of multiple companies. Why Workers Compensation Premium Fraud Matters Premium fraud can affect the broader workers’ compensation market because insurance pricing depends in part on accurate information about an employer’s exposure. If an employer allegedly underreports payroll, the insurer may receive less premium than it would have collected using accurate information. California’s Department of Insurance describes this type of activity as part of the underground economy and warns that businesses engaging in workers’ compensation premium fraud can gain an unfair competitive advantage over employers that comply with insurance and payroll requirements. The department also notes that businesses involved in underground-economy activity may engage in other forms of regulatory or financial misconduct. However, those broader risks should not be attributed to a particular defendant without evidence. In the Southern California towing case, the
Ventura County Secures $898,840 to Combat Workers’ Compensation Insurance Fraud
August 19, 2026 | JacobiJournal.com — Ventura County is strengthening its ability to investigate and prosecute workers’ compensation insurance fraud after the county District Attorney’s Office was awarded $898,840 from the California Department of Insurance for fiscal year 2026–2027. The funding was announced by the Ventura County District Attorney’s Office on July 24, 2026. According to the official announcement, the grant was awarded through the California Department of Insurance Workers’ Compensation Insurance Fraud Program and will support the District Attorney’s Workers’ Compensation Fraud Unit. The development is significant because the money is specifically designated for investigations and prosecutions involving workers’ compensation insurance fraud. Unlike general insurance-market announcements or regulatory rate changes, this funding directly supports criminal investigation and prosecution activity. For California employers, insurers, injured workers, and medical providers, the announcement demonstrates that local enforcement agencies continue receiving dedicated resources to identify and pursue suspected fraudulent activity. The Ventura County program uses a multidisciplinary team consisting of prosecutors, investigators, an investigative assistant, a forensic accountant, and an administrative assistant. The county said the team works to combat insurance fraud through investigations and prosecutions. Funding Targets Workers’ Compensation Insurance Fraud Workers’ compensation insurance fraud can involve different forms of alleged misconduct. Investigations may concern fraudulent claims, false statements, premium-related schemes, medical provider misconduct, or other conduct designed to improperly obtain or avoid payments within the workers’ compensation system. The Ventura County announcement does not identify a new defendant or specific fraud scheme associated with the $898,840 grant. Instead, the funding supports the county’s continuing enforcement infrastructure. That distinction is important. The July 24 announcement should be reported as an enforcement funding development, not as a newly filed fraud prosecution. The dedicated funding nevertheless gives investigators additional resources to pursue cases that may otherwise require substantial personnel and financial expertise. The inclusion of a forensic accountant is particularly relevant because financial records can be central to complex insurance fraud investigations. Investigators may need to examine payroll information, financial transactions, insurance records, medical billing, employment documentation, claims histories, or other records depending on the allegations involved. Why Dedicated Fraud Units Matter Insurance fraud investigations can require considerably more than a standard criminal investigation. Cases may involve insurance policies, claims records, employer information, medical documentation, financial transactions, and communications among multiple parties. A specialized unit can bring personnel with different areas of expertise together. Prosecutors can evaluate potential criminal charges, investigators can gather evidence, and forensic accounting personnel can analyze financial records. The Ventura County unit’s multidisciplinary structure reflects that approach. The county specifically identifies prosecutors, investigators, an investigative assistant, a forensic accountant, and an administrative assistant as members supported by the program. For workers compensation fraud cases, financial analysis can be particularly important where allegations involve premium manipulation, payroll reporting, billing, or other monetary conduct. At the same time, an investigation does not establish wrongdoing. Allegations must be supported by evidence, and defendants are entitled to the applicable legal process. California Continues Supporting Local Fraud Enforcement The Ventura County grant also illustrates the role of the California Department of Insurance in supporting local enforcement agencies. Rather than requiring every investigation to be handled exclusively at the state level, the Workers’ Compensation Insurance Fraud Program provides resources that can support local district attorneys and their specialized units. This structure allows local prosecutors and investigators to pursue cases arising within their jurisdictions while benefiting from funding specifically intended for workers’ compensation insurance fraud enforcement. The program is therefore relevant to the larger California insurance enforcement landscape. County-level investigations can address suspected misconduct that affects local employers, employees, insurers, medical providers, and other participants in the workers’ compensation system. The July 24 announcement confirms that Ventura County will continue this work during the 2026–2027 fiscal year. Financial Investigations Can Be Central to Fraud Cases The inclusion of a forensic accountant within Ventura County’s fraud unit is notable because many insurance fraud cases involve financial evidence. A forensic accountant can help investigators analyze financial records and identify discrepancies that may not be immediately apparent from ordinary claims documentation. Depending on the nature of a case, investigators could potentially need to compare payroll records against insurance applications, examine payment histories, trace financial transactions, or analyze business records. Such analysis can help investigators determine whether a suspected discrepancy represents an innocent administrative error or evidence that warrants further investigation. This distinction is particularly important in workers compensation fraud investigations because not every inaccurate record or disputed claim represents intentional fraud. Fraud allegations generally involve intentional conduct designed to obtain an improper benefit, payment, or advantage. Establishing that intent requires evidence beyond the existence of an error or inconsistency. Enforcement Can Affect Multiple Participants Workers’ compensation insurance fraud does not necessarily involve only injured employees. Depending on the circumstances, investigations can involve employers, employees, medical providers, attorneys, claims professionals, or other participants in the insurance process. Employer-related cases may involve allegations of misrepresenting payroll or employment information to reduce insurance costs. Claim-related investigations can involve allegations that an individual intentionally misrepresented an injury or circumstances surrounding a claim. Provider investigations can involve allegations concerning billing or treatment. The Ventura County announcement does not specify which categories will receive the greatest investigative attention during the new fiscal year. It simply confirms that the county’s specialized unit will continue investigating and prosecuting workers’ compensation insurance fraud. That makes the funding itself the news event rather than any particular allegation. Why the Development Matters to California Employers For employers operating in Ventura County, the grant serves as a reminder that workers’ compensation insurance compliance remains subject to enforcement. Employers have obligations concerning accurate payroll information, employee classification, insurance coverage, workplace injuries, and other aspects of the workers’ compensation system. Accurate records can help employers demonstrate compliance if questions arise. Maintaining organized payroll, employment, insurance, and injury records can also reduce confusion when claims or regulatory inquiries occur. Businesses should not interpret the announcement as evidence that every employer is under investigation. Rather, it demonstrates that the county has dedicated resources available to
Insurance Fraud Alert: California Targets Medical Provider Fraud 2026
July 31, 2026 | JacobiJournal.com – California regulators continue strengthening insurance fraud enforcement as the state’s workers’ compensation system remains focused on identifying fraudulent medical billing, illegal referral arrangements, medically unnecessary treatment, and providers whose workers’ compensation liens have been stayed during ongoing criminal investigations. Although no major statewide enforcement announcement was issued at the end of July, the California Department of Industrial Relations (DIR) and the Division of Workers’ Compensation (DWC) continue administering programs designed to detect, deter, and prevent provider-related fraud within the workers’ compensation system. Medical provider misconduct remains one of the most closely monitored forms of insurance fraud because fraudulent healthcare billing can significantly increase claim costs, delay benefit delivery for legitimately injured workers, and undermine confidence in California’s workers’ compensation program. State officials continue emphasizing that fraud prevention depends on strong oversight, coordinated investigations, and enforcement mechanisms that remove questionable claims from the adjudication process while criminal investigations proceed. The continued enforcement effort reflects California’s broader strategy of protecting injured employees while preserving the financial integrity of the workers’ compensation system. By monitoring suspicious billing practices and restricting payments connected to stayed liens, regulators seek to ensure that benefits are directed toward legitimate medical treatment supported by applicable workers’ compensation laws. California Continues Oversight of Medical Provider Fraud Medical providers play an essential role in California’s workers’ compensation system by evaluating injured employees, providing treatment, documenting medical conditions, and submitting reimbursement requests for authorized services. While the overwhelming majority of healthcare professionals comply with legal and ethical standards, regulators continue monitoring allegations involving insurance fraud that may affect medical billing and reimbursement. The Division of Workers’ Compensation maintains several anti-fraud measures intended to discourage improper billing practices. Among the most significant is California’s lien stay program, which restricts payment on workers’ compensation liens filed by providers who become subject to specified criminal charges involving fraud or abuse. These statutory provisions are designed to protect the workers’ compensation system while criminal proceedings remain pending. Rather than immediately determining civil liability, lien stays temporarily suspend payment on affected reimbursement claims until qualifying criminal cases are resolved. This process helps prevent potentially fraudulent medical claims from receiving payment before courts have an opportunity to consider the underlying criminal allegations. Fraud Investigations Frequently Examine Billing Practices Medical provider insurance fraud investigations may involve a variety of alleged misconduct depending upon the facts of each case. Regulators commonly review billing records, treatment documentation, referral relationships, reimbursement requests, and other financial records to determine whether services were properly provided and accurately reported. Investigations sometimes focus on allegations involving medically unnecessary treatment, billing for services that were never performed, duplicate reimbursement requests, unlawful kickback arrangements, or documentation that allegedly misrepresents the nature or extent of medical services. State investigators evaluate available evidence while coordinating with prosecutors and other enforcement agencies whenever criminal violations are suspected. California officials consistently note that allegations alone do not establish wrongdoing. Criminal investigations require evidence supporting the specific elements of alleged offenses, and providers remain entitled to due process throughout both criminal and administrative proceedings. Nevertheless, oversight remains an important component of California’s ongoing effort to combat insurance fraud within the healthcare sector. Why Stayed Liens Remain an Important Enforcement Tool California’s lien stay provisions continue serving as one of the state’s primary administrative tools for protecting the workers’ compensation system from questionable reimbursement claims connected to criminal fraud allegations. Under existing law, certain providers charged with qualifying fraud-related offenses may have their workers’ compensation liens automatically stayed while criminal proceedings remain pending. The purpose of the lien stay process is not to determine guilt or innocence. Instead, it temporarily prevents reimbursement from moving forward until the criminal justice system resolves the allegations. Regulators view this approach as an important safeguard that balances due process rights with the state’s responsibility to reduce opportunities for insurance fraud affecting workers’ compensation claims. By temporarily suspending payment on affected liens, California seeks to reduce financial exposure while allowing investigators and prosecutors sufficient time to complete complex fraud investigations. These safeguards also reinforce public confidence that questionable reimbursement requests will receive additional scrutiny before public or private insurance funds are distributed. Multi-Agency Cooperation Supports Ongoing Fraud Enforcement California’s enforcement strategy relies upon extensive cooperation among the Department of Industrial Relations, Division of Workers’ Compensation, California Department of Insurance, district attorneys, federal law enforcement agencies, and healthcare oversight organizations. Medical provider insurance fraud investigations frequently involve extensive financial analysis, medical record reviews, licensing information, and coordination between multiple regulatory agencies. Complex healthcare fraud cases often require investigators to examine thousands of billing records, patient files, reimbursement histories, and financial transactions. This collaborative approach allows agencies to identify broader fraud patterns while ensuring investigations remain supported by documentary evidence and applicable legal standards. Officials continue emphasizing that effective cooperation among regulatory and law enforcement agencies remains essential for detecting sophisticated fraud schemes, protecting injured workers, and preserving the long-term integrity of California’s workers’ compensation system. Continued Enforcement Reflects California’s Long-Term Anti-Fraud Strategy Rather than relying solely on criminal prosecutions after fraudulent activity has occurred, California continues strengthening administrative safeguards designed to detect insurance fraud earlier in the workers’ compensation process. Medical billing oversight, lien stay provisions, provider licensing requirements, utilization review standards, and interagency cooperation collectively support a broader strategy focused on protecting injured workers while safeguarding insurance resources. The Department of Industrial Relations and the Division of Workers’ Compensation continue emphasizing that fraudulent medical billing affects more than insurance carriers. Questionable billing practices can delay legitimate claim resolution, increase litigation costs, burden employers with higher workers’ compensation expenses, and reduce public confidence in the medical-legal process. By maintaining consistent oversight, California seeks to ensure that medical reimbursements are supported by appropriate documentation and comply with applicable workers’ compensation regulations. State regulators also continue educating employers, claims administrators, attorneys, and medical providers regarding compliance responsibilities. Fraud prevention efforts remain focused on encouraging accurate billing, proper documentation, ethical referral practices, and timely reporting of suspected misconduct involving insurance fraud. Why Medical Provider Fraud
Insurance Fraud Reform Advances with California SB 536 in 2026
July 29, 2026 | JacobiJournal.com — California lawmakers are advancing new legislation intended to strengthen the state’s fight against insurance fraud by giving workers’ compensation insurers additional tools to identify payroll discrepancies that may indicate premium fraud. Senate Bill 536 (SB 536), currently under legislative consideration, would establish a process allowing insurers to work with the California Employment Development Department (EDD) to compare employer payroll information during potential workers’ compensation fraud investigations. The proposal reflects California’s continuing effort to address one of the most costly forms of insurance fraud affecting the workers’ compensation system: employer payroll misrepresentation. According to the Assembly Insurance Committee analysis, dishonest employers may underreport payroll, misclassify employees, conceal wages, or otherwise provide inaccurate information that results in lower workers’ compensation insurance premiums than would otherwise be required. Supporters argue that these practices create an unfair competitive advantage while shifting financial burdens onto employers that accurately report payroll and comply with California law. By improving the ability of insurers to verify payroll information through EDD under carefully defined circumstances, legislators believe the bill could strengthen fraud detection while protecting honest businesses. SB 536 Targets Payroll Misrepresentation in Workers’ Compensation Insurance Unlike many enforcement actions that focus on criminal prosecutions after fraudulent activity has already occurred, SB 536 emphasizes earlier detection of potential insurance fraud through improved access to payroll verification. The proposal would permit insurers to submit employer wage records and employee counts to EDD for comparison against payroll information already maintained by the department. If discrepancies are identified, EDD would notify the insurer that inconsistencies exist. Under additional safeguards outlined in the legislation, insurers conducting an active workers’ compensation fraud investigation could request limited payroll summary information from EDD to determine whether additional investigation is warranted. The committee analysis specifies that the information would only be released when EDD determines the request is consistent with a legitimate workers’ compensation insurance fraud investigation and complies with applicable confidentiality requirements. Legislators emphasize that the proposal is not intended to provide unrestricted access to confidential employment records. Instead, the bill establishes multiple procedural safeguards governing when information may be requested, how it may be used, and the confidentiality obligations placed upon insurers receiving the information. Why Payroll Fraud Matters to California’s Workers’ Compensation System Workers’ compensation premiums are calculated using several factors, including payroll, employee classifications, workplace risks, and the nature of an employer’s operations. Because payroll directly influences premium calculations, intentionally underreporting wages or employee counts can significantly reduce insurance costs while transferring additional financial risk to insurers and compliant employers. The Assembly Insurance Committee explains that payroll or premium fraud can occur through several methods. Examples include underreporting total payroll, classifying employees into lower-risk occupations than they actually perform, misclassifying employees as independent contractors, paying wages in cash without reporting them, or failing to report overtime compensation accurately. Each practice can result in workers’ compensation premiums that fail to reflect the employer’s actual exposure. Supporters of SB 536 contend that stronger verification tools would improve the detection of insurance fraud involving payroll concealment while promoting a more level competitive environment for employers that accurately report workforce information. They further argue that reducing premium fraud ultimately benefits the broader workers’ compensation system by improving premium accuracy and reducing opportunities for abuse. Confidentiality Safeguards Remain Central to the Proposal Although SB 536 expands opportunities for payroll verification during fraud investigations, confidentiality protections remain a central feature of the legislation. The committee analysis repeatedly notes that EDD wage records are protected by both California law and federal unemployment insurance confidentiality regulations. Unauthorized disclosure of those records may result in criminal penalties and could potentially jeopardize federal unemployment insurance funding. To address those concerns, the bill limits disclosure to circumstances involving potential insurance fraud investigations and requires insurers to use the information solely for fraud investigation, underwriting, premium audits, premium collection, or required reporting activities. The legislation also prohibits insurers from using confidential payroll information for marketing purposes and generally prohibits sharing the information with law enforcement except through existing fraud referral procedures or other authorized circumstances. Additionally, insurers requesting payroll information would be required to reimburse EDD for the agency’s direct costs associated with processing requests. The proposal also authorizes EDD to require participating insurers to enter enforceable confidentiality agreements that may be terminated if safeguards are violated. Balancing Fraud Prevention and Privacy Protections During the Assembly Insurance Committee’s review, lawmakers acknowledged that expanding access to payroll information requires careful safeguards to protect employee privacy while strengthening insurance fraud investigations. The committee analysis explains that SB 536 attempts to balance those competing interests by allowing only limited payroll verification under defined circumstances rather than providing unrestricted access to confidential employment records. Under the proposal, insurers would first submit payroll information already provided by employers during the underwriting or premium audit process. The Employment Development Department (EDD) would then determine whether discrepancies exist between those records and the payroll information reported to the state. Only when statutory requirements are satisfied would limited payroll summary information become available for an active workers’ compensation insurance fraud investigation. Supporters contend that these safeguards help preserve confidentiality while improving the state’s ability to detect payroll concealment and premium evasion. They argue that protecting sensitive wage information remains essential even as California strengthens fraud enforcement tools. Potential Impact on Employers and Insurance Carriers If enacted, SB 536 could influence how insurers conduct premium audits and investigate suspected insurance fraud involving workers’ compensation policies. Insurance carriers would gain an additional verification resource when investigating allegations that payroll figures submitted during underwriting or policy renewals do not accurately reflect an employer’s workforce. For employers that accurately report payroll and employee classifications, the proposal could help promote a more level competitive marketplace. Businesses that comply with California law often argue that payroll concealment and premium evasion unfairly reduce operating costs for employers willing to violate insurance requirements. The legislation may also improve the efficiency of fraud investigations by allowing investigators to verify payroll discrepancies earlier in the investigative
Insurance Fraud Alert: California Cracks Down on Staged Collision Ring 2026
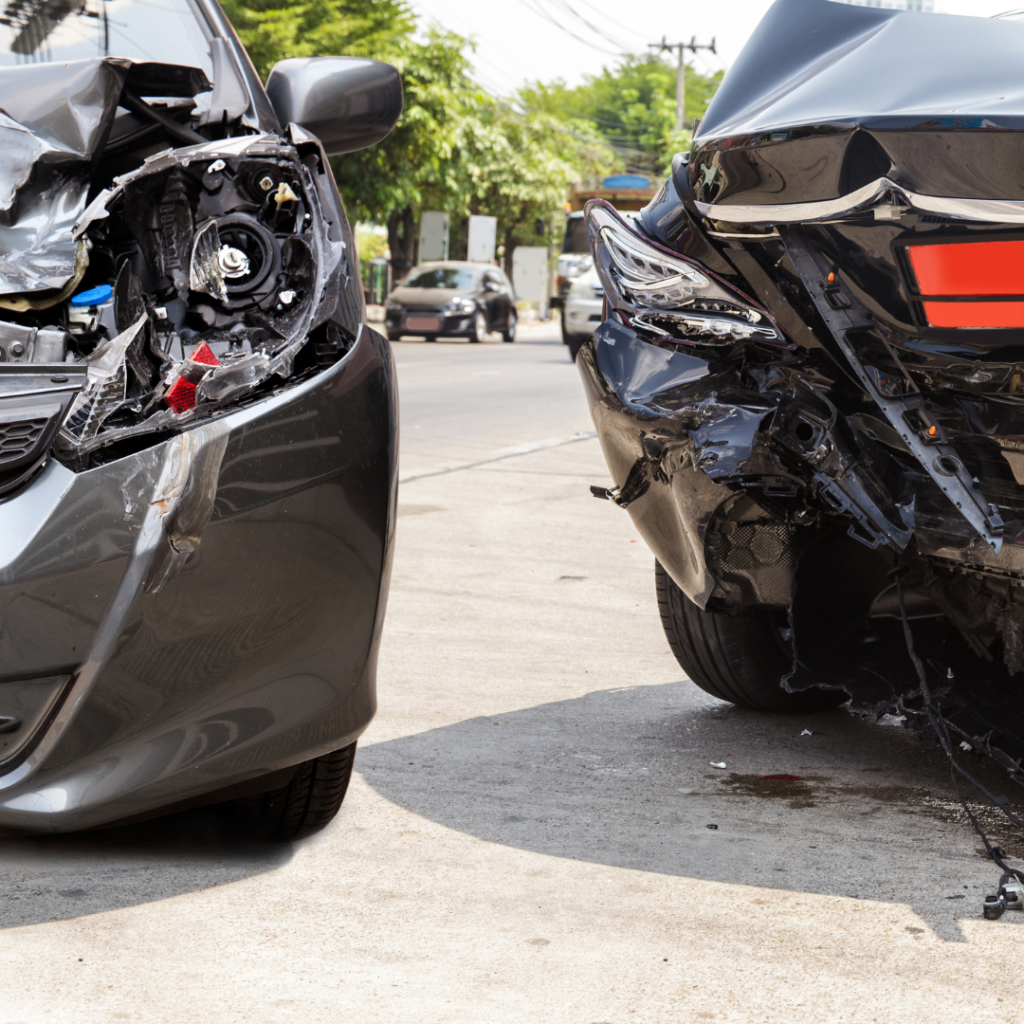
July 27, 2026 | JacobiJournal.com — California authorities continue intensifying insurance fraud enforcement after prosecutors charged four Southern California defendants in connection with an alleged staged automobile collision scheme designed to obtain fraudulent insurance benefits. According to the California Department of Insurance, investigators believe the defendants intentionally caused vehicle crashes, submitted insurance claims, and sought medical treatment to support alleged injury claims associated with the staged incidents. The investigation demonstrates how organized insurance fraud schemes can extend beyond false vehicle damage claims. Authorities allege the defendants attempted to strengthen insurance claims by obtaining medical treatment after the collisions, creating documentation that investigators contend was intended to support bodily injury claims and increase insurance payouts. Prosecutors further allege that one of the staged crashes involved an innocent motorist who was not connected to the scheme. California officials emphasize that staged collisions create risks extending far beyond financial losses. Innocent motorists may suffer physical injuries, emotional distress, vehicle damage, increased insurance premiums, and lengthy claim disputes while law enforcement agencies devote significant resources to investigating organized criminal activity targeting insurance companies. How Investigators Uncovered the Alleged Staged Collision Scheme According to the California Department of Insurance, the investigation began after the Upland Police Department reported multiple suspicious traffic collisions to the Inland Empire Automobile Insurance Fraud Task Force. Officers observed similarities among several crashes that raised concerns the incidents may have been intentionally arranged rather than accidental. The task force conducted a detailed investigation involving the California Department of Insurance, the California Highway Patrol, the San Bernardino County District Attorney’s Office, and the Riverside County District Attorney’s Office. Detectives reviewed police reports, witness statements, insurance claim records, and other evidence to determine whether the collisions were connected. Authorities ultimately concluded there was sufficient evidence to allege that several crashes had been deliberately orchestrated for financial gain. The investigation resulted in felony charges against four Southern California defendants, although each defendant remains presumed innocent unless proven guilty in court. What Prosecutors Allege Happened During the Collisions Investigators allege that the defendants intentionally crashed into one another during separate incidents in San Bernardino County while later presenting the collisions as legitimate traffic accidents. Authorities contend the alleged scheme was designed to generate insurance fraud claims for vehicle damage, bodily injuries, and related insurance benefits. According to prosecutors, one alleged collision occurred in Upland during June 2025 when two vehicles occupied by the defendants intentionally struck each other. Detectives allege everyone involved later sought medical treatment after the collision in an effort to support injury claims and increase insurance compensation. Investigators also allege that an earlier collision in Montclair targeted an unsuspecting motorist who had no connection to the alleged scheme. California officials state that staged collisions become especially dangerous when innocent drivers unknowingly become victims of organized insurance fraud operations. Why Fake Injury Claims Increase the Severity of Insurance Fraud Cases Authorities allege that seeking unnecessary medical treatment after staged crashes can significantly increase the financial impact of insurance fraud investigations. Bodily injury claims often involve medical evaluations, diagnostic testing, rehabilitation services, prescription medications, wage-loss benefits, and other insurance payments that substantially exceed the cost of vehicle repairs alone. Investigators believe fraudulent injury claims also consume valuable healthcare resources while creating additional burdens for insurers, medical providers, and claims professionals responsible for evaluating legitimate accident victims. Each allegedly fraudulent claim requires extensive review before insurers can determine whether benefits should be paid. California regulators continue emphasizing that fraudulent injury claims can have consequences beyond insurance losses. Staged collisions expose emergency responders, medical professionals, and innocent motorists to unnecessary risks while diverting investigative resources away from legitimate public safety concerns. How Multi-Agency Cooperation Strengthened the Investigation The Inland Empire Automobile Insurance Fraud Task Force played a central role throughout the investigation by coordinating resources among multiple law enforcement agencies. Detectives combined accident reconstruction, insurance claim analysis, surveillance evidence, and witness interviews to evaluate whether the reported crashes were consistent with legitimate traffic collisions. The investigation also benefited from cooperation between local police departments, prosecutors, insurance investigators, and state fraud specialists. This collaborative approach allowed authorities to compare evidence from multiple incidents while identifying alleged relationships among the defendants. California officials continue relying on multi-agency partnerships to combat increasingly sophisticated insurance fraud schemes involving organized criminal activity. By sharing investigative resources and financial evidence, agencies improve their ability to identify staged collision networks before additional fraudulent claims are submitted. How Staged Collision Schemes Affect Honest Drivers Staged collision investigations extend far beyond the insurance companies that receive fraudulent claims. California officials warn that innocent motorists can become unintended victims when organized groups intentionally create traffic crashes to generate insurance payouts. These individuals may suffer physical injuries, emotional trauma, property damage, increased insurance premiums, and lengthy claims disputes despite having no involvement in the alleged scheme. The California Department of Insurance noted that investigators believe one of the alleged staged collisions deliberately targeted an unsuspecting driver. Prosecutors allege the innocent motorist was drawn into the fraudulent operation solely to create the appearance of a legitimate accident capable of supporting insurance and injury claims. Officials continue emphasizing that insurance fraud involving staged collisions represents a serious public safety concern because every intentionally caused crash places other motorists, passengers, pedestrians, and first responders at unnecessary risk. Preventing these schemes protects both consumers and California’s transportation system. Why Insurance Fraud Investigations Focus on Medical Documentation Medical records often become a critical component of insurance fraud investigations involving staged collisions. After a reported traffic accident, insurance companies typically review emergency room reports, physician evaluations, diagnostic imaging, rehabilitation records, and billing documentation when assessing injury claims. Investigators allege that fraudulent medical treatment obtained solely to support fabricated injury claims may increase the overall financial impact of an alleged fraud scheme. Detectives therefore examine the timing of treatment, accident reports, surveillance evidence, witness statements, and claim documentation to determine whether the reported injuries are consistent with the circumstances surrounding the collision. California authorities stress that legitimate accident victims should never hesitate to